

Dollarwise: Budget & Tracking

- 1.16K Reviews
- 3.3
- Downloads
- 100,000+
Our take on Dollarwise: Budget & Tracking from Appgk
I spent time with Dollarwise: Budget & Tracking as a personal finance app, looking at what it feels like to use repeatedly rather than judging it only by its short promise to help rewrite your money story. My overall impression is that it is aimed at people who want a more deliberate relationship with spending, but who may not need the complexity of a full banking platform. It is free to install, carries an Everyone age rating, and comes from HammerMedia, so the first barrier to trying it is low. The more important question is whether its approach fits the way you actually manage money.
That distinction matters because finance apps live or die by routine. A budgeting tool can look appealing on the first day and still become useless if recording a purchase feels slow, if the information is hard to interpret, or if the app does not recover gracefully when you return after a busy week. Dollarwise sits in a category where simplicity is valuable, but simplicity also creates trade-offs. I would consider it most suitable for someone building a spending habit, checking personal outgoings, or trying to put structure around irregular expenses. I would be more cautious about recommending it as the only tool for detailed household accounting or serious financial planning.
How Dollarwise feels during everyday use
A finance app that needs to stay out of your way
The first thing I look for in a budgeting app is not a flashy dashboard. I want to know whether I can open it, understand where I am, and make a useful update without turning a small task into an administrative session. Dollarwise: Budget & Tracking makes sense in that context. Its purpose is practical: give spending a place to be recorded and reviewed so that money decisions become visible instead of vague.
For a typical weekday, the useful workflow is easy to imagine. I buy lunch, pay for transport, and make a small household purchase. Rather than relying on memory at the end of the month, I would use the app while those transactions are still fresh, then return later to see whether the pattern matches my plan. That habit is more important than any single screen. The app can only help if I keep the information current, and the design of a finance tool should encourage quick, repeatable check-ins.
Best Parts of Dollarwise: Budget & Tracking
Things to Keep in Mind About Dollarwise: Budget & Tracking
My advice is to begin with a narrow purpose instead of trying to rebuild your entire financial life immediately. Track the spending area that causes the most uncertainty first. That might be food, subscriptions, casual shopping, or transport. After a week or two of consistent entries, the app becomes more useful because the numbers reflect your real behavior rather than an optimistic estimate.
The strongest practical use is turning vague spending anxiety into a regular review habit. That is a different job from connecting every account, preparing tax records, or replacing a bank statement. Users who understand that boundary are likely to get more from Dollarwise than people expecting an all-in-one financial command center.
News and Features Related to Dollarwise: Budget & Tracking

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Speed expectations and the cost of a small delay
Perceived speed matters unusually much in this category. If opening the app or recording a purchase feels like a chore, I am less likely to do it at the moment it matters. Dollarwise is best judged by whether its everyday actions feel direct and understandable, not by how elaborate its presentation looks. A budgeting app does not need to overwhelm the screen with information; it needs to help me make a decision quickly.
On a newer, reasonably maintained device, I would expect the current version, 6.4.0, to be the sensible version to try because it represents the developer’s present release rather than an older installation. Still, I would not choose a finance app solely on the assumption that a newer version guarantees perfect responsiveness. Performance can vary with the phone, available storage, operating-system condition, and how much information has accumulated inside an app.
Don't want to read the full review?
One useful habit is to separate “slow app” from “slow workflow.” If I am entering too much detail for every minor purchase, the process itself may be the problem. A lighter routine—recording the amount and the most useful category, then doing a deeper review later—can make the experience feel faster without sacrificing the purpose of tracking. This is one of the trade-offs I would explain to a friend before recommending it.
What happens during heavier budgeting sessions
The demanding moments are unlikely to be a single quick entry. They are more likely to happen when I review several days at once, reorganize spending, or try to make sense of a month that contains many different purchases. That is when navigation, clarity, and the app’s ability to keep my place become more important than the opening screen.
Screenshots
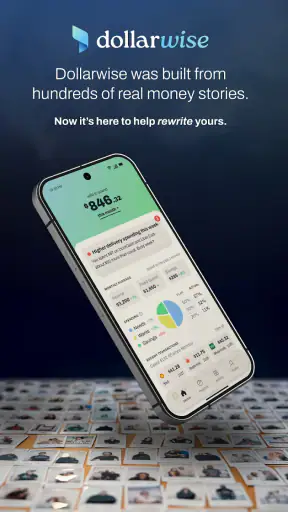
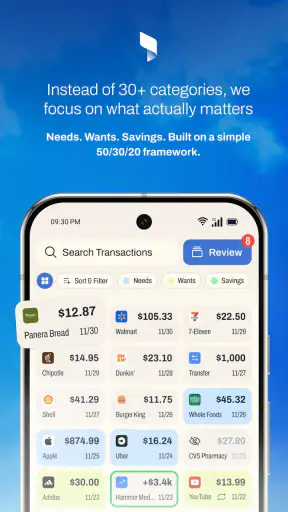
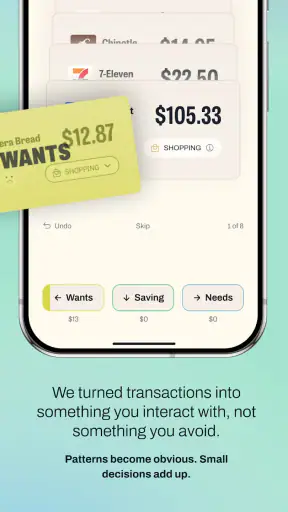
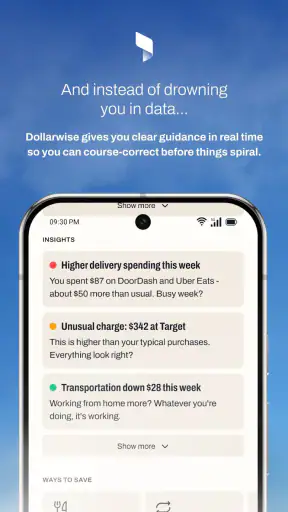
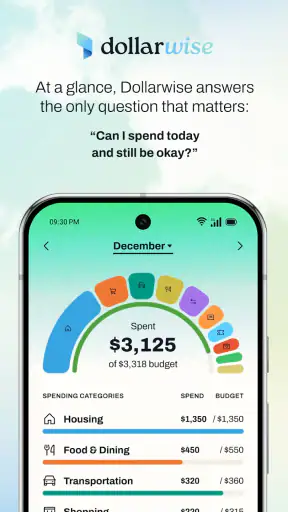
I would avoid postponing all tracking until a large end-of-month session. That approach creates two problems: memory becomes less reliable, and a large batch of entries makes the task feel heavier. A better workflow is to make brief updates throughout the week and reserve the longer session for interpretation. In practice, I might use a quiet Sunday moment to look for recurring overspending, then decide on one adjustment for the next week rather than attempting a complete financial makeover.
This also gives me a way to judge resource demands realistically. A finance tracker should not need the same level of attention as a media-heavy app, but any app can feel cumbersome when it is asked to display or process a long history at once. Keeping the review focused has a second benefit: it reduces the temptation to react emotionally to every individual purchase.
A non-obvious strength of this workflow is that it separates capture from reflection. Capture is about accuracy and speed; reflection is about patterns and choices. If I use Dollarwise for both jobs at the same time, I risk making every entry too complicated. If I keep those stages separate, the app has a better chance of becoming a sustainable tool rather than another abandoned self-improvement project.
Reliability, recovery, and trust
Reliability is more than whether an app opens. In personal finance, I care about whether my routine survives interruptions. A phone call, a low-battery moment, or simply forgetting to finish an entry can break the flow. My approach would be to make small updates, then revisit the app soon afterward rather than assuming that one long session will always be available.
I also recommend treating the app as a record that deserves regular attention, not as an invisible automatic safety net. Before relying on any budgeting tool for an important decision, I would compare its totals with the source information I normally use, such as bank activity or receipts. This is not a criticism unique to Dollarwise; it is good practice whenever a financial app depends on information being entered or maintained correctly.
Recovery matters when returning after a gap. If I have ignored the app for several days, I would not try to reconstruct every detail from memory in one rushed sitting. I would start with the transactions I can verify, mark the uncertain period mentally, and use the next week to restore a dependable routine. That approach protects the usefulness of the record even when my own consistency is imperfect.
The app’s average rating is 3.3 from around two thousand ratings, with roughly one thousand reviews. I read that as a sign to keep expectations measured rather than assuming the experience will be equally smooth for everyone. A middling public response does not automatically make the app poor, but it does support a cautious trial: use it with a manageable set of expenses first, see whether the workflow feels dependable on your device, and only then decide whether it deserves a central place in your routine.
Device constraints and installation decisions
Dollarwise supports Android 7.0 and later, which gives it a broad compatibility range for Android users with older phones. That is useful if I am trying to manage money on a device that is no longer receiving the newest operating-system features. At the same time, compatibility is not the same as identical performance. Older hardware may have less free storage, less memory available for switching between apps, or a slower response when handling a long history.
For that reason, I would keep the phone reasonably tidy before judging the app. Closing unrelated apps, leaving some storage available, and installing the current release are simple steps that make the test fairer. If a device struggles generally, a finance app may feel inconvenient even when the underlying task is modest. I would also avoid making the app the sole place where I remember important financial obligations until I have used it long enough to trust my own process.
The Everyone rating makes Dollarwise approachable for a wide audience, including people who are beginning to learn budgeting. Younger users or anyone sharing a device should still think about who can access the phone and how comfortable they are entering financial information there. An age label is useful for suitability, but it does not replace sensible device security or careful judgment about personal records.
Free entry, paid possibilities, and value
The app is free to download, which makes experimentation straightforward. I like that model for a budgeting tool because the first test should be about fit: can I understand the workflow, maintain it for several days, and gain something useful from reviewing my spending? Those questions are more important than committing immediately to a paid financial service.
There are in-app purchases ranging from about fifteen dollars to around five hundred dollars per item. That is a wide span, so I would pay close attention to the purchase screen and the exact value of any option before spending money. I would not assume that installing the free app means every useful function will remain free, nor would I purchase an expensive option simply because it appears during a moment of financial frustration.
My practical test would be simple: use the free experience long enough to establish a real routine, then ask whether a paid feature solves a problem I actually have. If I only need occasional spending awareness, a paid upgrade may not be necessary. If a particular feature saves meaningful time every week, the calculation changes—but I would still compare that cost with a basic spreadsheet or another budgeting service before deciding.
Who should use it, and who should choose something else?
I would recommend Dollarwise to someone who wants a focused place to think about spending and needs encouragement to look at money regularly. It may also suit a user who prefers a personal budgeting routine over a complicated financial dashboard. The app’s free starting point makes it reasonable for students, first-time budgeters, or anyone testing whether manual tracking can become a habit.
I would be less enthusiastic for a household that needs several people to maintain one shared financial picture, or for someone whose main requirement is automatic account aggregation and detailed reporting. In those cases, a spreadsheet may offer more control, while a bank-connected budgeting service may reduce manual entry. A dedicated financial-planning product could also be better for long-term goals, investments, debt schedules, or tax-related organization.
There is another important exception: people who dislike recording transactions should not expect the app alone to change that preference. Dollarwise can provide a structure, but it cannot make missing information accurate. If I know I will avoid manual updates, I would choose an alternative built around the automation I need rather than blaming a tracker for a mismatch between its workflow and my habits.
My performance verdict after weighing the trade-offs
Dollarwise: Budget & Tracking is worth a careful trial, especially if I want a free entry into personal spending awareness and use an Android device running version 7.0 or later. Its real value is not the promise of instant financial transformation. It is the possibility of creating a repeatable moment in which I record what happened, review the pattern, and make one sensible adjustment.
I would keep the first test deliberately small: choose one spending area, update it consistently, and check whether the app remains comfortable during both quick entries and a longer weekly review. That experiment reveals more than a single first impression. It also helps separate device-related sluggishness, an overly ambitious tracking method, and genuine friction in the app itself.
HammerMedia’s app has enough appeal to earn a place on the shortlist for beginners, but the 3.3 average means I would not recommend it blindly. The broad Android compatibility and free installation lower the risk of trying it, while the in-app purchase range makes careful spending decisions important. My final view is balanced: choose Dollarwise when a simple, personal tracking routine is the goal; choose a more connected or collaborative alternative when automation, shared access, or advanced financial control matters more than habit-building.
For me, that is the clearest way to judge its performance. A finance app succeeds when it remains usable during ordinary life, including rushed purchases, missed days, and imperfect records. If Dollarwise helps you return to your money without making the process feel intimidating, it can be genuinely useful. If it becomes another task you postpone, a different kind of budgeting tool will serve you better.
Dollarwise: Budget & Tracking FAQ
What is Dollarwise: Budget & Tracking used for?
Dollarwise: Budget & Tracking is designed to help you organize personal finances in one place. After setting up income, recurring bills, spending categories, and savings goals, you can review where your money goes and monitor progress over time. It is especially useful for users who want a clearer budgeting routine without relying on spreadsheets or complicated financial software.
Is Dollarwise: Budget & Tracking suitable for beginners?
Yes, the app is generally approachable for beginners because its main purpose is to make budgeting easier to understand. New users can start with a simple income-and-expenses setup, then add categories or goals as needed. However, the quality of your results depends on entering transactions consistently and configuring the budget realistically rather than expecting the app to manage finances automatically.
Does Dollarwise: Budget & Tracking connect to bank accounts automatically?
Before downloading, users should check the current app-store description and in-app settings to confirm whether bank synchronization is available in their country and plan. Budgeting apps can differ considerably in supported banks, currencies, and connection providers. If automatic linking is unavailable, you may need to enter transactions manually, which offers more control but requires regular maintenance.
Is my financial information safe in Dollarwise: Budget & Tracking?
Financial privacy should be considered before using any budgeting application. Review Dollarwise’s privacy policy, requested permissions, data-storage practices, encryption information, and whether optional account synchronization involves a third-party service. Avoid entering sensitive details that the app does not require, use a strong device lock, and keep the application updated. No budgeting tool should be treated as a replacement for careful account security.
Is Dollarwise: Budget & Tracking free to download and use?
The app’s availability, free features, subscriptions, and optional in-app purchases may vary between Android and iOS and can change with updates. Check the relevant store listing before installing, paying particular attention to trial periods and recurring billing terms. The free version may be enough for basic expense tracking, while advanced reports, unlimited categories, synchronization, or extra planning tools could require payment.











